 This article is a follow up on “If you must speculate: Force Protection Inc.” published on April 15th, 2011 and is intended as a closer examination of the YTD 2011 FRPT order book, along with some additional speculation on the future growth prospects in 2011 and 2012.
In the above article we pointed out that the total worth of the company to a prospective acquirer was about 150 mln. as of April 15th (share price $4.54). The stock has risen to $4.80 per share as of close of market on May 4th, 2011, a gain of some 5.7% in just under 3 weeks.
The following comment are taken from the April 15th article:
The company made the following comments on May 2nd:
“US contracts for spares, sustainment and upgrades for the existing fleet of vehicles already in service make it likely that FRPT will grow its revenue over 2010, even without winning these new contracts. With improved gross margins, and no lawsuits to settle, it seems reasonable that earnings will be higher for 2011 (albeit recognized in the back half of the year).
"The combination of today's announcement, other awards previously secured in 2011, and the portion of funded backlog at December 31, 2010 that is anticipated for delivery this year, results in solid visibility for the Company's previously disclosed outlook for 2011. As such, the Company reiterates its expectation of year-over-year growth in total revenue and earnings, with the majority of its 2011 full year financial results anticipated to be recorded in the second half of the year."
An update on the numbers:
So far in 2011, the company has announced 5 awards worth 211 mln. This averages to a 42 mln. award every 24 days. At this rate, there would be 15 awards announced in 2011 with a value of 631 mln. (see below). As indicated in the April 15th article, we also believe a second follow on UK MoD order is all but a foregone conclusion. Since FRPT’s Ocelot (a light protected patrol vehicle (LPPV)) is scheduled to replace the UK military's Snatch Land Rover, and the snatch land rover fleet consists of some 991 built vehicles, we think it is reasonable to further estimate that the UK indeed is interested in more than 200 of the Ocelot’s that comprised the initial order. We further believe an award for an additional 200 vehicles will be announced during 2011 for the following reasons:.
So far in 2011, the company has announced 5 awards worth 211 mln. This averages to a 42 mln. award every 24 days. At this rate, there would be 15 awards announced in 2011 with a value of 631 mln. (see below). As indicated in the April 15th article, we also believe a second follow on UK MoD order is all but a foregone conclusion. Since FRPT’s Ocelot (a light protected patrol vehicle (LPPV)) is scheduled to replace the UK military's Snatch Land Rover, and the snatch land rover fleet consists of some 991 built vehicles, we think it is reasonable to further estimate that the UK indeed is interested in more than 200 of the Ocelot’s that comprised the initial order. We further believe an award for an additional 200 vehicles will be announced during 2011 for the following reasons:.
a) the vehicle is currently in production
b) The UK MoD has indicated that the procurement is operationally “urgent” with initial delivery required in 2011.
Here are the numbers:
We would add a third speculation based on information obtained from the quarterly report of one of FRPT’s closest competitors - Oshkosh.
On April 28th, OSK made the following disclosure in their quarterly earning call:
| Contracts: | Value | Date | Days |
| 1/1/2011 | |||
| 2011 | $ 11,400,000.00 | 3/30/2011 | 88 |
| $ 46,600,000.00 | 4/6/2011 | 7 | |
| $ 27,400,000.00 | 4/21/2011 | 15 | |
| $ 18,800,000.00 | 5/2/2011 | 11 | |
| $ 106,900,000.00 | 5/3/2011 | 1 | |
| Total | $ 211,100,000.00 | Avg. | |
| Avg. | $ 42,220,000.00 | 24.4 | |
| 4.87 pts. | $ 2,056,114.00 | ||
| Annualized orders | 15 | ||
| Annualized Rev. | $ 631,569,672.13 | ||
| 4.87 pts. | $ 30,757,443.03 | ||
| UK MoD 2nd order | $ 280,000,000.00 | ||
| Tot. w/ An. Rev. | $ 911,569,672.13 | ||
| 4.87 pts. | $ 44,393,443.03 |
The key speculations outlined in the previous article were as follows:
a) FRPT has great prospects for winning awards worth some additional 2.6 bln in 2011
b) Given the low enterprise value, and large pending awards, the company may be a prospective take-over target for a larger defense contractor, or a private equity group.
“…We received a stop work order in the quarter related to our previous award for 250 M-ATV ambulances. This is a development program, and U.S. government is investigating another option for delivery of ambulances into the theater…”
Unfortunately, FRPT doesn’t have an ambulance variant of any of their vehicles. Or do they? A recent DoD reviewspecifically references the following:
Speculation aside, If the above contract award projections are even approximately accurate, and if FRPT does not win the Canadian and Australian contracts referenced in the original article, than FRPT is still a company with 44 mln. in operating income just from 2011 annualized order intake alone (4.87% x 911 mln).
If this figure is added to the 27.2 mln in operating income from the funded backlog as of Dec. 31st, 2010 (4.87% x 560 mln) – the investor is paying 150 mln. (as previously illustrated) for a company with 72 mln. in virtually guaranteed operating income – that is to say, 48% of the operative purchase price of the company at April 15th, is already being returned to the purchaser through operating income.
We think the above estimates are better than “approximately accurate”, since the company had previously advised, that few awards should be expected in the first half of the year, and yet over 200 mln. has already been announced. We think the estimates for 2011 order intake are conservative.
b) If the 150 mln. in cash on the balance sheet is subtracted from the total equity in the company at Dec. 31st, 2010, the buyer today has some 178 mln. in remaining hard assets which would only need to be liquidated at .44 cents on the dollar in order to cover the common.
In other words, there is almost no risk left in the purchase of FRPT common stock, while the upside potential is nothing short of massive.
Although the operating margin is not very strong as a percentage, it does represent a remarkable return on capital given the small enterprise value (and even more remarkable given the offset from future operating income). Even if the company was not awarded a second UK MoD order, the company would still earn about 31 mln. from the conservative projection of 632 mln. in new orders for 2011, when combined with the operating income from the funded backlog, the investor is assured a 39% return of the effective purchase price.
We believe this information along with the company’s affirmation of the 2011 guidance provides a sufficient margin of safety to purchase the shares as an investment.
“In March 2011, the program will execute a Limited User Test (LUT) at Yuma Proving Ground, Arizona, to examine a unit’s ability to execute missions with the MRAP Family of Vehicles modified with an ISS and the operational effectiveness of the FPI Cougar CAT II ambulance variant. “
The above information might be of interest to investors for the following reasons:
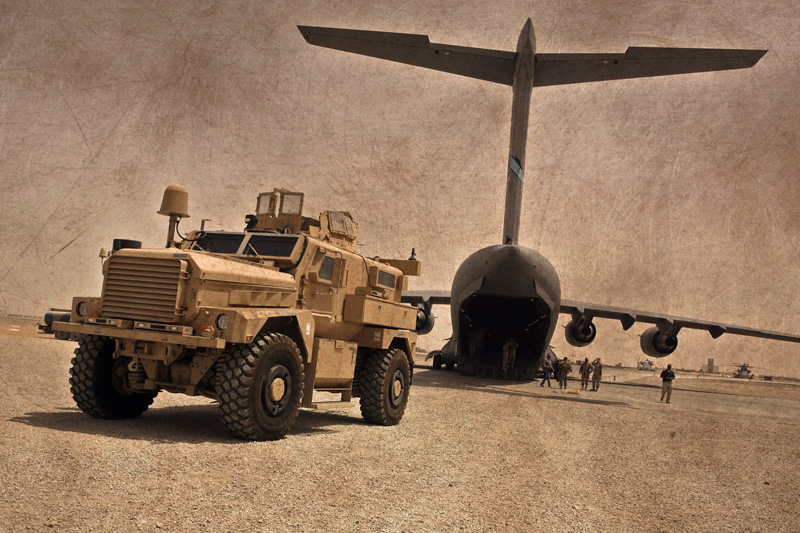
a) The press release above from FRPT on May 2nd was part of an announcement of some 125 mln. in upgrade to the existing cougar fleet – an indication that the military is pleased with these vehicles (which have survived some 300 IED explosions through 2004 without the loss of a single life), an intends to keep them in service for some time.
b) The DoD report praises FRPT’s vehicle (particularly with the just ordered 106 mln. ISS upgrades) over one of the competitors MRAP ambulance offering, which they refer to as “not operationally effective” (we now know that OSK is also out)
c) Since OSK received a “stop work order” on the 250 vehicle, 161 mln. order around the same time the DoD was retesting the modified cougars (a vehicle already in operation and production); it seems likely that FRPT’s product may well be the replacement for this urgent operational need OSK referenced in their quarterly CC.
d) If the US continues to invest in the 4000 Cougars that have already been fielded as indicated by the multiple upgrades, and since the MRAP was also selected by the UK’s MoD as part of their Ridgback and Mastiff programs, then it is not a stretch to imagine that this vehicle, which has been extensively proven in theatre, and has two world class endorsements by the US and UK, is likely to be the vehicle of choice for the Canadian TAPV program.
Speculation aside, If the above contract award projections are even approximately accurate, and if FRPT does not win the Canadian and Australian contracts referenced in the original article, than FRPT is still a company with 44 mln. in operating income just from 2011 annualized order intake alone (4.87% x 911 mln).
If this figure is added to the 27.2 mln in operating income from the funded backlog as of Dec. 31st, 2010 (4.87% x 560 mln) – the investor is paying 150 mln. (as previously illustrated) for a company with 72 mln. in virtually guaranteed operating income – that is to say, 48% of the operative purchase price of the company at April 15th, is already being returned to the purchaser through operating income.
We think the above estimates are better than “approximately accurate”, since the company had previously advised, that few awards should be expected in the first half of the year, and yet over 200 mln. has already been announced. We think the estimates for 2011 order intake are conservative.
Liquidation value and risk:
a) If this virtually guaranteed operating income is subtracted from the effective purchase price of 150 mln, the real price to the buyer today is 78 mln net.
In other words, there is almost no risk left in the purchase of FRPT common stock, while the upside potential is nothing short of massive.
Although the operating margin is not very strong as a percentage, it does represent a remarkable return on capital given the small enterprise value (and even more remarkable given the offset from future operating income). Even if the company was not awarded a second UK MoD order, the company would still earn about 31 mln. from the conservative projection of 632 mln. in new orders for 2011, when combined with the operating income from the funded backlog, the investor is assured a 39% return of the effective purchase price.
We believe this information along with the company’s affirmation of the 2011 guidance provides a sufficient margin of safety to purchase the shares as an investment.
No comments yet. Be the first to share your thoughts!